Compare Scuba Diving Insurance Options: Coverage Tiers, Evacuation Limits, and Policy Mechanics
Underwater exploration introduces physiological liabilities that standard travel policies explicitly exclude. When ambient pressure alters gas absorption within human tissues, minor equipment failures or rapid ascents can trigger decompression sickness or arterial gas embolism. Treating these conditions requires specialized hyperbaric oxygen therapy and emergency air evacuation from remote coastal regions. Without dedicated financial protection, a single medical emergency beneath the surface can generate six-figure hospital and transport invoices.
Navigating specialty underwriting requires careful scrutiny of policy exclusions, depth thresholds, and primary versus secondary payer clauses. Divers often assume general health plans or credit card travel benefits cover aquatic mishaps, only to discover strict hazardous-activity carve-outs after an accident occurs. Evaluating specialty plans demands an analytical approach that matches personal dive profiles with contractual realities. This reference dissects the structural mechanics, coverage variations, and risk dynamics required to make informed underwriting decisions.
Understanding “compare scuba diving insurance options”
Defining Specialty Aquatic Underwriting
To effectively compare scuba diving insurance options, practitioners must distinguish between general travel medical policies and dedicated dive accident coverage. Standard travel insurance treats recreational submersion as an extreme sport, frequently capping coverage at shallow depths or excluding hyperbaric chamber treatments entirely. Specialty dive policies are underwritten specifically for barotrauma, decompression illness, and marine animal injuries, offering direct payment guarantees to recompression facilities worldwide.
Multi-Perspective Risk Assessment
Insurance brokers, dive operators, and medical directors evaluate policy adequacy through different lenses. Charter captains prioritize proof of evacuation coverage to ensure seamless emergency transfers from remote offshore reefs. Medical facilities require immediate financial guarantees before initiating multi-hour hyperbaric chamber sessions. Meanwhile, individual divers must balance annual premium costs against deductible structures, geographic reach, and coverage limits for non-diving medical emergencies.
Oversimplification Hazards in Policy Selection
Selecting a policy based solely on annual premium price creates severe coverage gaps. A budget plan might advertise high overall medical limits while imposing a strict thirty-meter depth restriction or excluding enriched air nitrox mixes. If an injury occurs at thirty-two meters, the insurer can legally void the entire claim due to breach of warranty. Careful readers examine fine-print exclusions rather than relying on marketing brochures.
Deep Contextual Background
Evolution from Commercial Salvage to Recreational Protection
Early underwater insurance developed alongside commercial hard-hat salvage operations in the late nineteenth century, focusing on marine vessel liability rather than individual diver physiology. As autonomous open-circuit diving gained popularity during the nineteen-sixties, civilian decompression accidents surged. Existing health insurers lacked actuarial data on hyperbaric medicine, resulting in widespread claim denials and bankruptcies among injured recreational divers.
Emergence of Dedicated Dive Safety Organizations
During the early nineteen-eighties, specialized non-profit networks like the Divers Alert Network emerged to bridge the gap between emergency medicine and underwater recreation. By establishing twenty-four-hour medical hotlines and collecting epidemiological dive data, these organizations enabled underwriters to price aquatic risk accurately. Modern specialty plans evolved from those foundational frameworks, integrating global air-ambulance logistics with direct-billing hyperbaric networks.
Conceptual Frameworks and Mental Models
Primary Versus Secondary Payer Hierarchy
Understanding payment priority prevents prolonged administrative disputes during medical crises. Primary policies pay eligible medical expenses first, regardless of whether the insured holds domestic health insurance. Secondary policies act as excess coverage, requiring injured divers to submit claims to their domestic health provider first and wait for formal denial letters before releasing funds. Relying on secondary coverage overseas often forces patients to pay thousands of dollars upfront out of pocket.
Geographic Proximity and Evacuation Logistics
Medical evacuation value depends entirely on the distance between a dive site and the nearest operational recompression chamber. In regions with dense hospital infrastructure, ground ambulance transport suffices. Across remote Pacific atolls or liveaboard routes, air-ambulance extraction requires fixed-wing aircraft equipped to maintain sea-level cabin pressure. Evaluating evacuation caps requires calculating worst-case transport distances from planned destinations.
Depth, Gas Mix, and Training Alignment
Underwriters enforce strict alignment between certified training credentials and operational parameters. A policy covering recreational air diving automatically lapses if an uncertified diver uses mixed-gas trimix or penetrates an overhead shipwreck. Coverage validity operates on a conditional contract model: every dive must remain within the bounds of the insured’s recognized agency certification.
Key Categories or Variations
Annual Dive Accident Plans
Annual plans cover unlimited recreational dive trips over a twelve-month period, providing hyperbaric treatment, emergency evacuation, and accidental death benefits. These policies suit frequent travelers who complete multiple local and international dive excursions yearly.
Short-Term Per-Trip Dive Policies
Designed for occasional vacationers, short-term policies provide targeted aquatic medical protection for durations ranging from seven to thirty days. Premiums are calculated per trip, offering cost efficiency for individuals who dive once annually.
Comprehensive Travel Plus Dive Bundles
Hybrid policies merge standard trip cancellation, baggage delay, and flight interruption protection with specialized underwater medical riders. Travelers booking expensive liveaboard charters use these bundles to safeguard non-refundable deposits against weather or illness.
Technical and Mixed-Gas Endorsements
Standard recreational plans typically cap depths at forty meters and prohibit staged decompression stops. Technical tiers extend coverage to deeper profiles, closed-circuit rebreathers, and overhead cave or wreck environments, provided the diver holds corresponding technical certifications.
Gear Loss and Equipment Damage Riders
Specialty equipment riders reimburse repair or replacement costs for regulators, dive computers, and underwater camera housings damaged during transit or lost at sea. Policies enforce strict depreciation schedules and require police or operator incident reports.
Professional Instructor and Divemaster Liability
Commercial policies protect certified dive leaders against third-party bodily injury lawsuits, negligence claims, and equipment rental liabilities. Recreational accident policies strictly exclude any incident occurring while the insured receives financial compensation.
Decision Logic for Coverage Selection
When readers compare scuba diving insurance options, the selection process begins by auditing existing domestic health coverage for international exclusions. Divers traveling abroad twice or more annually generally gain better financial protection by pairing an annual primary dive accident plan with a separate general travel policy. Conversely, single-trip vacationers booking high-cost charters should prioritize comprehensive hybrid plans with strong trip-interruption clauses.
Detailed Real-World Scenarios
Scenario One: Decompression Sickness on a Remote Liveaboard
A diver completes four repetitive multi-level dives daily aboard a vessel anchored two hundred miles offshore. On the final afternoon, tingling numbness develops in both shoulders accompanied by severe joint pain. The vessel captain contacts the insurer’s twenty-four-hour medical desk, which arranges a pressurized helicopter evacuation to a mainland hospital. Because the policy features primary payer status and unlimited evacuation limits, the insurer guarantees the fifty-thousand-dollar transport cost directly, preventing treatment delays.
Scenario Two: Uncertified Depth Violation Invalidates a Claim
A newly certified Open Water diver, restricted to eighteen meters, descends to thirty-five meters along a steep wall to photograph pelagic fish. Rapid ascent causes pulmonary barotrauma and arterial gas embolism. Upon reviewing the downloaded dive computer profile, the insurance adjuster discovers the depth violation and denies the hyperbaric treatment claim. Contractual terms strictly void coverage when divers exceed agency depth limits.
Scenario Three: Non-Diving Illness During an International Dive Trip
Two days before boarding a charter boat, a traveler contracts severe bacterial pneumonia requiring local hospitalization and flight rescheduling. A standalone dive-accident-only policy refuses reimbursement because the illness did not result from underwater submersion. Having a complementary travel medical policy covers the hospital stay and rebooking fees, illustrating the danger of relying exclusively on dive-specific plans.
Scenario Four: Flooded Underwater Camera Housing in Transit
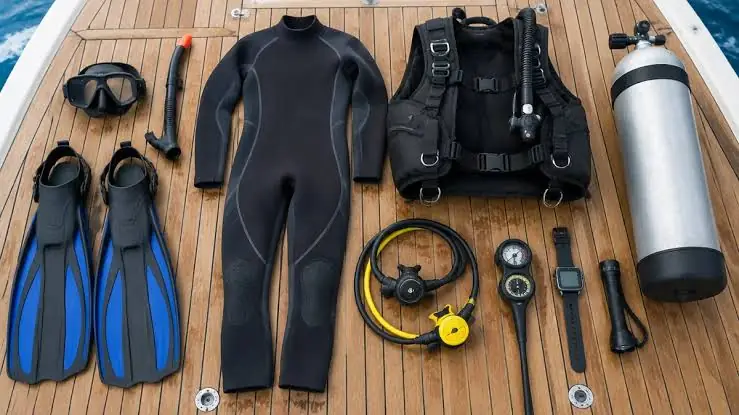
During rough boat transfers, a heavy equipment crate shifts, cracking an aluminum camera housing and destroying a professional mirrorless body. The diver submits a claim under a general airline baggage policy, which caps payouts at fifteen hundred dollars. A dedicated dive equipment rider covers the full replacement value minus a modest deductible, provided the owner maintained original purchase receipts and serial numbers.
Planning, Cost, and Resource Dynamics
Direct Premium Outlays Versus Deductible Structures
Specialty dive coverage remains remarkably affordable relative to the catastrophic medical risks it mitigates. Entry-level annual plans cost less than a single tank rental day, while comprehensive family or technical tiers scale proportionally. Choosing zero-deductible plans eliminates out-of-pocket surprises during emergencies, whereas higher deductibles slightly reduce upfront annual fees.
Hidden Cost Variability and Evacuation Caps
Low-cost travel riders frequently cap emergency medical evacuation at twenty-five thousand dollars, an amount easily exhausted by a single international air ambulance flight. When you compare scuba diving insurance options, scrutinizing evacuation sub-limits prevents catastrophic balance billing. True specialty plans provide between two hundred fifty thousand and one million dollars in dedicated transport coverage.
Tools, Strategies, and Support Systems
Twenty-Four-Hour Hyperbaric Medical Hotlines
Leading dive insurers operate round-the-clock emergency dispatch centers staffed by physicians trained in hyperbaric and undersea medicine. These specialists coordinate directly with local clinics, verify chamber availability, and authorize direct payment guarantees before patients arrive.
Digital Policy Cards and Emergency Action Plans
Modern providers supply downloadable wallet cards displaying policy numbers, international collect call numbers, and evacuation authorization codes. Storing laminated physical copies inside dry boxes ensures boat crews can initiate claims even if the diver is incapacitated.
Dive Computer Log Downloads for Claim Verification
Adjusters routinely request digital dive logs to verify ascent rates, maximum depths, and surface intervals following a decompression incident. Maintaining accurate computer timestamps and adhering to conservative decompression algorithms substantiates claim legitimacy.
Pre-Trip Medical Screening Consultations
Insurers offer non-emergency medical information lines where divers can consult physicians regarding prescription medications, recent surgeries, or sinus congestion before flying. Clarifying fitness-to-dive status prevents unexpected policy invalidations overseas.
Risk Landscape and Failure Modes
The Secondary Payer Cash-Flow Trap
Many budget travel policies operate strictly on a reimbursement model. Injured divers must pay hospital bills via personal credit cards and submit translated receipts months later. In regions where hyperbaric chambers demand upfront cash deposits before closing the hatch, secondary reimbursement policies create dangerous treatment delays.
Geographic and Political Sanctions Exclusions
International underwriters exclude coverage in nations subject to government travel advisories or economic sanctions. Traveling to restricted jurisdictions voids medical evacuation guarantees regardless of premium payment status.
Pre-Existing Condition Carve-Outs
Undisclosed cardiovascular conditions, asthma, or prior decompression injuries frequently trigger automatic claim denials. Insurers require documented medical clearance from a diving physician before covering individuals with significant medical histories.
Governance, Maintenance, and Long-Term Adaptation
Annual Coverage Audits Before Renewal
Divers frequently upgrade their skills from Open Water to Advanced, Nitrox, or Technical levels without updating their insurance tier. Reviewing policy terms annually ensures coverage boundaries expand alongside new certifications and deeper dive profiles.
Policy Verification Checklist
-
Payer Status: Confirm whether the policy pays primary or secondary to domestic health insurance.
-
Depth and Gas Limits: Verify that maximum covered depth and gas blends match upcoming dive itineraries.
-
Evacuation Cap: Ensure air-ambulance limits exceed three hundred thousand dollars for remote destinations.
-
Direct Billing: Confirm the insurer issues direct payment guarantees to hyperbaric chambers worldwide.
-
Non-Diving Coverage: Check whether non-aquatic illnesses or injuries require a separate travel medical plan.
Measurement, Tracking, and Evaluation
Leading Indicators of Policy Adequacy
Evaluating coverage strength before departure involves verifying active membership status, confirming beneficiary designations, and testing emergency hotline numbers from international mobile carriers. Proactive verification eliminates administrative friction during actual crises.
Lagging Indicators and Claim Documentation Standards
Following an incident, claim resolution speed depends on thorough documentation. Divers must retain signed physician diagnoses, itemized hospital invoices, dive computer profile exports, and witness statements from dive guides. Organized records accelerate reimbursement timelines and prevent administrative rejections.
Common Misconceptions and Oversimplifications
The Myth That Domestic Health Insurance Covers Overseas Diving
Most domestic health plans either exclude out-of-country medical care entirely or categorize scuba diving as an uncovered hazardous pursuit. Even when emergency stabilization is covered, domestic insurers rarely pay for specialized international air-ambulance transfers.
Assuming Credit Card Travel Benefits Include Hyperbaric Care
Premium travel credit cards frequently advertise complimentary emergency medical evacuation. However, fine print almost universally restricts transport to the nearest adequate medical facility, excluding specialized hyperbaric centers, and voids coverage during high-risk sports.
Believing Dive Shop Liability Protects Individual Divers
Signing a standard liability waiver before boarding a dive boat releases the operator from negligence claims, while offering zero medical protection to the diver. Individuals remain personally responsible for all rescue, evacuation, and chamber expenses unless insured independently.
Ethical, Practical, and Contextual Considerations
Financial Responsibility Toward Rescue Networks
Operating air-ambulance aircraft and maintaining hospital hyperbaric chambers incurs immense fixed overhead costs. Carrying adequate insurance ensures that remote medical facilities remain financially solvent and capable of serving local communities alongside visiting divers.
Honesty in Dive Computer Reporting
Altering dive logs or concealing risky dive profiles during claim investigations constitutes insurance fraud. Transparent reporting preserves actuarial stability across the diving community and keeps specialty premiums affordable for responsible practitioners.
Conclusion
Underwater exploration demands meticulous preparation that extends beyond physical conditioning and mechanical gear maintenance. Financial and medical risk management forms an invisible but essential layer of life support beneath the surface. When divers take time to compare scuba diving insurance options rigorously, they protect themselves against catastrophic evacuation costs and ensure immediate access to specialized hyperbaric care. Ultimately, matching primary-payer coverage, high evacuation limits, and certified depth parameters to personal dive ambitions allows practitioners to explore the ocean with genuine peace of mind.